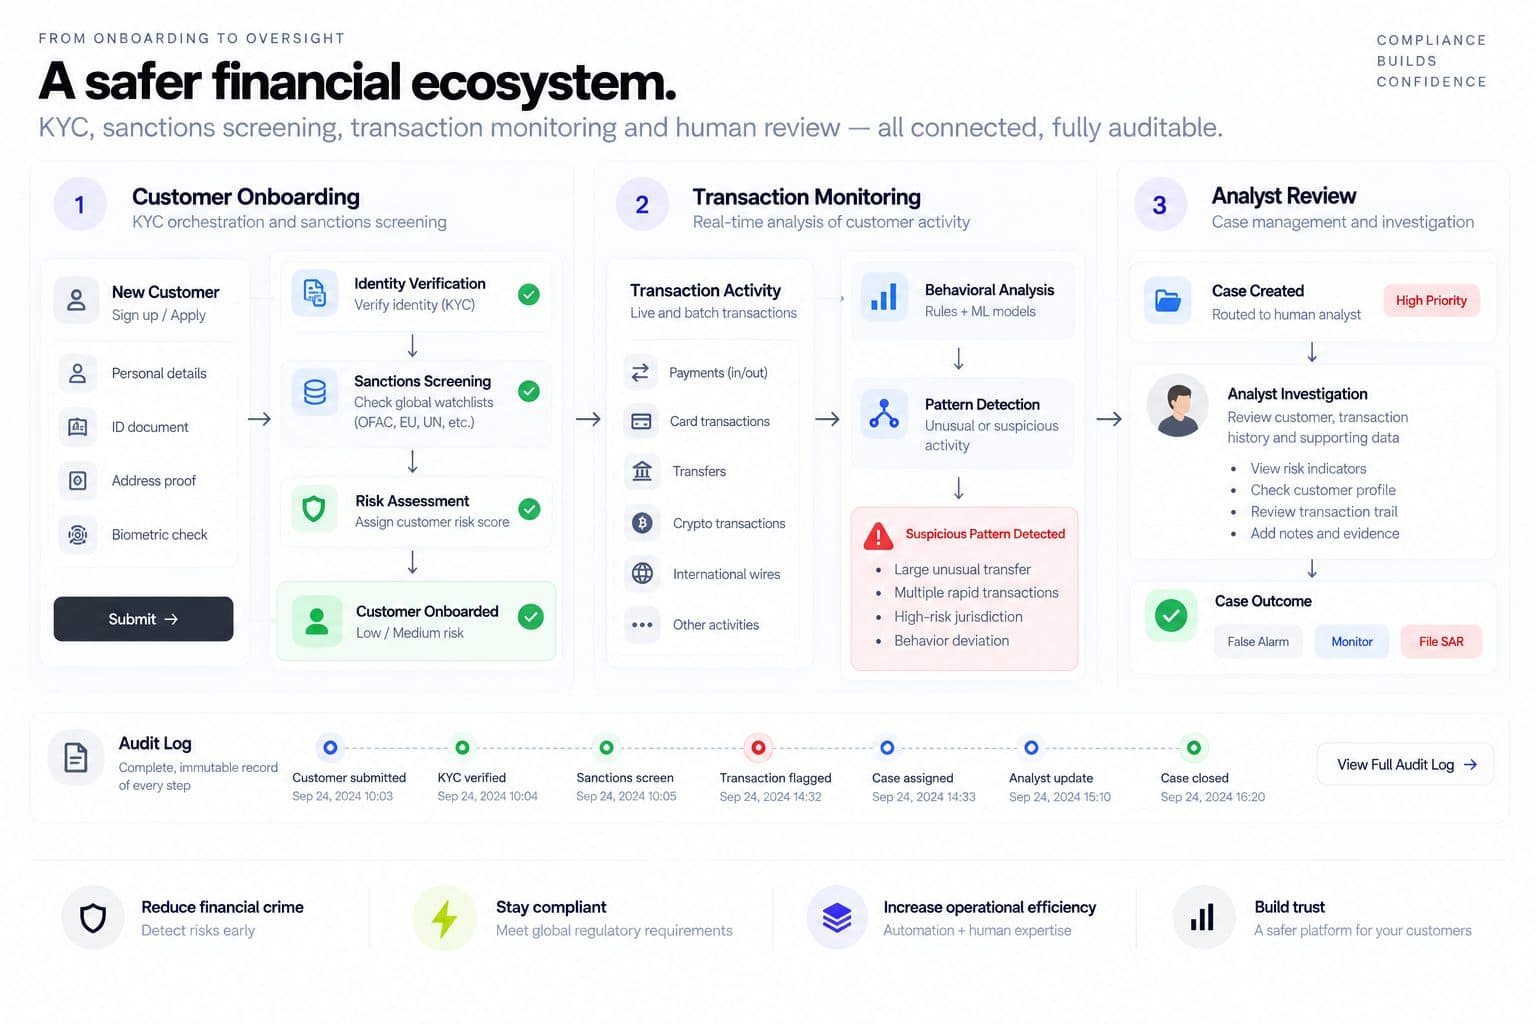
KYC onboarding, transaction monitoring, and sanctions screening built as real infrastructure, not a checklist someone updates after an audit finding. Lending decisions and SAR filings stay with your compliance officers. We build the pipeline that gets them accurate, current information to decide on.
Compliance infrastructure, engineered before growth outpaces it
Why fintech compliance failures rarely start as a technology gap
The regulatory actions that actually land, weak anti-financial crime controls, gaps in transaction monitoring, sanctions screening failures, SAR filing violations, tend to share a pattern: a compliance program that didn't scale at the same pace as onboarding volume and transaction growth. A 2025 European Banking Authority opinion found that more than half of serious AML and CFT compliance failures traced back to improper deployment of RegTech tools already in place, not the absence of technology. The tools existed. The architecture and operational discipline around them didn't keep up.
We are not a compliance program, an auditor, or your BSA officer. What we build is the infrastructure layer, KYC orchestration, transaction monitoring pipelines, sanctions screening, that is supposed to scale with your business and often doesn't, engineered with the same rigor whether you're processing a thousand transactions a day or a million.
What this breaks into
KYC and onboarding orchestration. Identity verification, document checks, and risk scoring wired together into one onboarding flow instead of five disconnected vendor integrations, built and orchestrated through n8n so the flow is auditable and each step's outcome is logged. Covered in the general automation pattern on our n8n Workflow Automation page.
Transaction monitoring pipelines. Rule-based and pattern-based flagging of transaction activity, tuned against your actual transaction patterns rather than a generic threshold set that produces either constant false positives or missed activity. Case queues route flagged activity to your analysts with the context they need to investigate quickly.
Sanctions and watchlist screening. Automated screening against relevant watchlists at onboarding and on an ongoing basis, with match review routed to a human analyst rather than an automatic block or clear decision made without oversight.
KYC document processing. ID documents, proof of address, and business registration documents extracted and validated automatically, with confidence scoring and human review on anything uncertain, covered in depth on our AI Document Processing page.
Audit trail and evidence infrastructure. Every automated decision and every human review logged in a way that supports both an internal audit and a regulatory examination, covered in the general pattern on our AI Compliance Automation page, extended here to the specific evidence a BSA or AML examination actually requires.
What we deliberately don't build
Automated lending or credit decisions. Fair lending law applies fully to AI-driven decisions, and regulators have been explicit that black-box models fail scrutiny; adverse action notices need specific, explainable reasons a model can actually produce. Building a compliant lending decision model is a specialized model risk management discipline of its own, governed by guidance like SR 11-7, not general software engineering. If that is what you need, we will tell you honestly that it calls for a specialized partner alongside us, not instead of proper diligence.
Automated SAR filing without a compliance officer's sign-off. Suspicious activity reporting is a regulated, accountable decision. We build the pipeline that surfaces the pattern and assembles the supporting evidence quickly; the decision to file, and the filing itself, stays a human, licensed compliance function.
Why Flowagenz
Infrastructure you own outright.
Full ownership of every pipeline, integration, and audit log built for you. Nothing depends on a Flowagenz-run system to keep your monitoring and onboarding flows running.
Based in Salem, Tamil Nadu.
Western-grade engineering at a rate structure offshore delivery makes possible.
Real overlap, not vague promises.
Async-first communication with working hours that overlap US Eastern mornings, UK afternoons, and Australian business hours on the same day.
We build for the volume you're growing into, not just the volume you have today.
A KYC flow or monitoring pipeline that works at your current transaction count and buckles at ten times that count is exactly the failure pattern regulators keep finding. We scope for where your growth is actually headed.
How it works
01
01
Compliance and volume scoping.
We map your current KYC, monitoring, and screening processes against your actual transaction and onboarding volume, including where it's headed over the next year, not just where it is today.
02
02
Architecture design with your compliance team.
Pipeline design reviewed against your BSA officer's and compliance team's actual requirements before any code gets written, since they own the regulatory outcome this infrastructure supports.
03
03
Build and integration.
KYC orchestration, monitoring pipelines, and screening built and tested against real transaction patterns and connected to your case management and audit systems.
04
04
Handover with full audit documentation.
Complete documentation of what the system does and does not decide automatically, handed to your compliance team as well as your engineers. Timeline varies significantly by scope; a KYC onboarding flow moves faster than a full transaction monitoring pipeline.
FAQ
Frequently Asked Questions
Everything you need to know about our process and digital systems.
No, and we will not claim it does. AML and BSA compliance is a program your compliance officer runs, informed by your regulator and legal counsel. What we build is the infrastructure that program depends on, engineered to scale with your business, but it is not a substitute for the program or its human judgment calls.
Build the infrastructure before volume outpaces it
Tell us where your current KYC or monitoring process is straining against your actual growth, and we will scope the infrastructure with your compliance team on a short call.